Case and deadline assessment
We examine the current position, document material gaps and agree which findings affect the hmrc representation scope.
Evidence-led support for enquiries, disclosures and formal correspondence.
Finance and tax problems become expensive when records, deadlines and decisions are considered separately or only at year end.
Evidence-led support for enquiries, disclosures and formal correspondence. We begin with the present situation, the people affected and the evidence required. That keeps the work proportionate and avoids committing to a platform, filing route or provider before the requirement is understood.
Tax and accounting work is accepted only after the responsible entity, adviser, engagement terms and any required professional or regulatory arrangements are confirmed.
Every output is tied to an owner, dependency, review point and acceptance condition in the written scope.
We examine the current position, document material gaps and agree which findings affect the hmrc representation scope.
This output is defined in the written hmrc representation scope with its owner, dependencies, review point and acceptance criteria.
Relevant records, periods, deadlines and approval responsibilities are confirmed before preparation or submission work.
This output is defined in the written hmrc representation scope with its owner, dependencies, review point and acceptance criteria.
The right route depends on where the business is now, not on a pre-selected product.
Visible review points keep commercial decisions, specialist responsibilities and delivery evidence clear.
Clarify the present situation, users, risks, deadlines and desired result.
Review the systems, records, evidence and dependencies that affect the work.
Confirm outputs, exclusions, ownership, timing, fees and acceptance points.
Complete the agreed work through visible stages and decision gates.
Document the result, responsibilities, controls and next actions.
These items help us identify the right first step.
Explain the business problem once. We will route the enquiry across the relevant Master Nest divisions.
Start with the problem →Explore adjacent services without losing the wider business context.
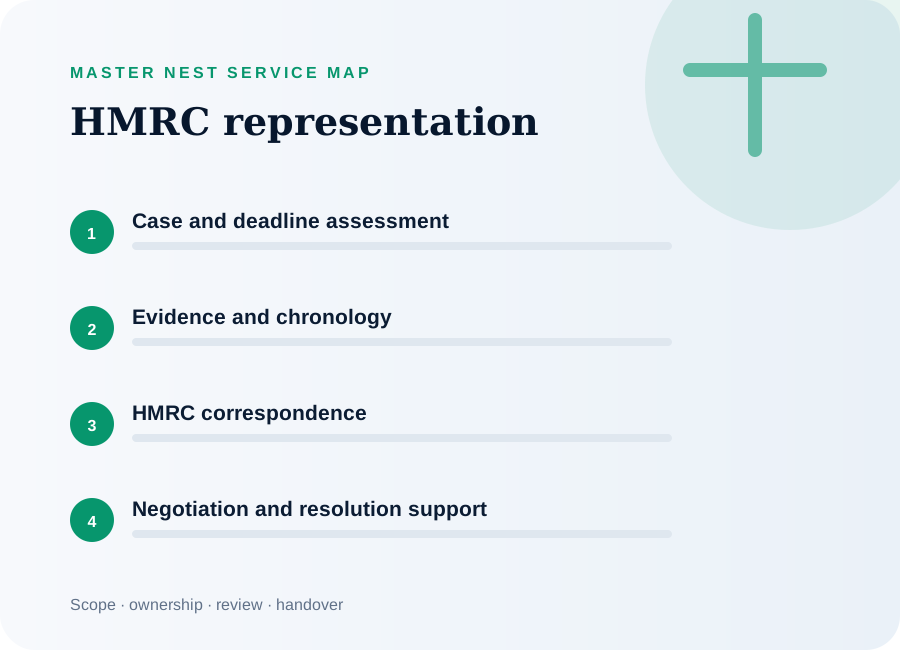
The scope may cover case and deadline assessment, evidence and chronology, hmrc correspondence, and negotiation and resolution support. The final combination depends on your current position and required outcome.
We review complexity, systems, records, dependencies and support required, then provide a written proposal before paid work begins.
Timing is confirmed after discovery because access, data quality, provider approvals, statutory deadlines and review availability can materially affect delivery.
Yes. We first establish access, responsibilities and decision rights so existing suppliers, software and professional advisers can be coordinated safely.
The latest accounts, returns or relevant HMRC correspondence, a summary of income, entities and ownership, and any immovable deadline or commercial constraint.
Yes. Where the requirement crosses technology, finance or payments, the dependencies and responsible parties are made explicit in the scope.
Tell us what needs to improve, what you have tried and what a useful result would look like.